You open your banking app and there it is:
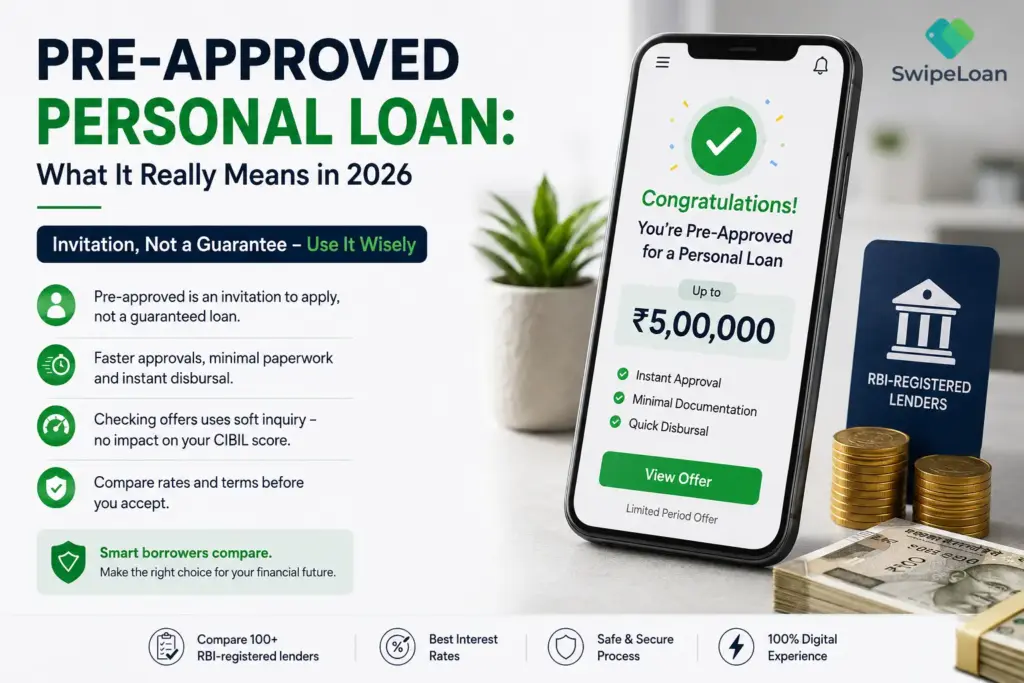
“Congratulations! You’re pre-approved for a personal loan up to ₹5 lakh.”
It feels like the money is already yours. It isn’t — not yet.
A pre-approved offer is a strong signal, not a signed cheque. Misread it,
and you can budget around cash that never arrives, or accept terms you never
actually compared. Read it correctly, and it becomes one of the fastest,
lowest-friction ways to borrow in 2026.
This guide explains exactly what a pre-approved personal loan means,
whether it can still be rejected, how it affects your CIBIL score,
and how to use these offers without getting caught out.
Key Takeaways
-
“Pre-approved” means the lender is inviting you to apply
— it’s not a promise. They can still say no if your income or credit
score drops.
-
Just looking at a pre-approved offer does not hurt your
CIBIL score. Your score is only affected when you
accept and apply.
-
These offers usually go to people with a good credit score
(often 710 or above) and an existing account with
the lender.
-
Pre-approved doesn’t mean it’s the cheapest deal.
Always compare the rate with other lenders before you say yes.
What Does a Pre-Approved Personal Loan Actually Mean?
A pre-approved personal loan is a pre-screened offer a lender extends to you
based on your existing credit profile — essentially an invitation to apply,
not a confirmed loan. The lender has already run a soft check and believes
you’re likely to qualify, which is why the process feels near-instant.
Because the groundwork is done, pre-approved loans typically disburse in
minutes once you accept — with minimal fresh documentation. That speed is
the real benefit. But “pre-approved” describes the lender’s confidence,
not a legal commitment to lend.
Here’s what the label does and doesn’t promise:
| Pre-approval does mean |
Pre-approval does not mean |
| The lender pre-screened your profile |
Your loan is guaranteed |
| Approval probability is high |
The rate is the best available to you |
| Faster processing, less paperwork |
The offer can’t be withdrawn |
| No fresh hard credit check just to view it |
Final terms are locked before you accept |
Does a Pre-Approved Loan Guarantee Approval?
No — a pre-approved personal loan does not guarantee final approval.
The offer is an invitation to apply and can be withdrawn if your income,
employment, or credit score changes adversely between the offer and your
acceptance.
Think of it as a conditional green light. The conditions are usually
invisible until final verification: a fresh credit pull, income confirmation,
and a check that nothing has changed since the offer was generated.
Common reasons a pre-approved offer still falls through:
-
Your CIBIL score dropped after the offer
(a missed EMI or a new hard inquiry).
-
You took on new debt, raising your
obligations-to-income ratio.
-
Income or employment couldn’t be verified, or recently changed.
-
The offer expired — most have a validity window.
-
Documents submitted don’t match the pre-screened profile.
Important:
A pre-approved personal loan should be treated as a high-probability
starting point rather than a completed loan. Avoid taking on new credit
while an offer is active because changes to your credit profile, income,
or debt position can affect final approval.
Does Checking a Pre-Approved Offer Hurt Your CIBIL Score?
Simply viewing a pre-approved offer does not hurt your CIBIL score,
because it’s generated from a soft inquiry. Your score is only affected
when you formally accept and the lender runs a hard inquiry for final
approval.
This distinction is the most misunderstood part of pre-approved lending.
Soft Inquiry
A background check used to determine whether you may qualify
for an offer.
Score impact: 0
Hard Inquiry
A formal credit check performed when a lender processes
your application.
Possible small, temporary score dip.
Where a Pre-Approved Offer Touches Your CIBIL Score
1
View Offer
Soft inquiry
0 impact
2
Compare
Still soft
0 impact
3
Accept
Hard inquiry
Small dip
You can explore and compare pre-approved offers freely;
only acceptance is recorded on your report.
Per credit-bureau guidance, checking a pre-approved personal loan offer
is generally treated as a soft inquiry, allowing you to explore options
without affecting your CIBIL score. A hard inquiry can be recorded when
you formally accept and the lender processes final approval.
Pre-Approved vs Pre-Qualified: What’s the Difference?
Pre-approved and pre-qualified sound identical but signal different levels
of lender confidence. A pre-approved offer means the lender already screened
your actual credit data and invited you; a pre-qualified estimate is a
lighter, often self-reported check that indicates you might qualify.
Pre-approved is the stronger signal.
The practical takeaway: a pre-approved offer usually reflects data the lender
already holds about you, often as an existing customer, so its terms tend
to be more concrete. A pre-qualified figure is closer to an educated guess.
| Type |
What It Means |
Stage |
| Pre-qualified |
“Based on limited information, you may be eligible.”
|
Weaker, earlier stage
|
| Pre-approved |
“Based on your credit profile, we’re inviting you to apply.”
|
Stronger, later stage
|
Remember:
Neither is a final sanction — both still require verification before disbursal.
Who Gets Pre-Approved Personal Loan Offers?
Pre-approved personal loan offers typically go to borrowers with a healthy
credit history — often a CIBIL score above 710 — and,
frequently, an existing relationship with the lender.
Consistent repayment behaviour and stable income are what put you on a
lender’s pre-screened list.
Existing customers tend to receive more offers because the lender already
sees their salary credits, balances, and repayment track record. But strong
external borrowers can also receive offers, especially through marketplaces
that match profiles across multiple lenders.
You’re more likely to be pre-approved if you have:
-
A CIBIL score of 710+
(750+ may unlock better rates)
-
A clean repayment history with no recent defaults
-
Stable, verifiable income and low existing debt
-
An existing account or loan in good standing with the lender
Should You Accept a Pre-Approved Loan Straight Away?
Not automatically. A pre-approved offer is fast and convenient, but
“pre-approved” says nothing about whether the rate is competitive.
In 2026, mainstream personal loan rates can start near
9.99% p.a. for strong-credit borrowers, and a
pre-approved offer isn’t guaranteed to match the market’s best.
Always compare before you commit.
The smarter approach:
Treat your pre-approved offer as one quote among several. Because viewing
offers is generally a soft inquiry, you can line up multiple pre-approved
and standard options side by side before choosing one.
A pre-approved personal loan optimises for speed,
not necessarily price. The pre-approved rate is a
benchmark to beat, not a ceiling to accept.
Compare Before You Accept
A pre-approved offer is a great starting point — but it’s still just one
lender’s quote. SwipeLoan is a credit-matching loan marketplace that
connects you with 100+ RBI-registered lenders, so you can hold your
pre-approved offer up against real alternatives in a single view.
Because comparing uses soft checks, your CIBIL score stays untouched until
you choose. See your pre-approved-style offers side by side. Then accept
the one that actually fits — not just the first notification that lands
in your inbox.
Frequently Asked Questions
Is a pre-approved personal loan guaranteed?
No. A pre-approved personal loan is an invitation to apply,
not a guarantee. The lender can still perform final verification
and may withdraw or decline the offer if your credit profile,
income, employment or debt position has changed.
Does checking a pre-approved loan affect CIBIL?
Simply viewing a pre-approved offer generally uses a soft
inquiry and does not affect your CIBIL score. A hard inquiry
can occur when you formally apply and the lender processes
your application.
What CIBIL score is needed for a pre-approved personal loan?
Pre-approved offers are generally targeted at borrowers with
healthy credit histories. A CIBIL score around 710 or above
may improve the likelihood of receiving an offer, while
750+ can potentially provide access to better rates.
Each lender uses its own eligibility criteria.
Is a pre-approved personal loan cheaper?
Not necessarily. Pre-approved loans are primarily designed
to provide convenience and faster processing. The interest
rate and fees may not be the lowest available to you.
Comparing offers before accepting can help you find a more
competitive total cost.
Can a pre-approved personal loan be rejected?
Yes. Final approval can still depend on updated credit,
income, employment, existing debt and document verification.
A change in any of these factors can affect the final decision.
Does SwipeLoan provide personal loans directly?
No. SwipeLoan is an AI-powered credit-matching loan marketplace
and Lending Service Provider that connects borrowers with
RBI-registered lenders. The partner lender determines the
interest rate, approves the loan and disburses the funds,
subject to its own eligibility criteria and applicable rules.
Conclusion
-
A pre-approved personal loan is an invitation to apply,
not a guarantee — it can still be withdrawn before
disbursal.
-
Viewing offers is generally a soft inquiry;
a formal application can trigger a hard inquiry.
-
Pre-approval optimises for speed, not necessarily price
— the rate may not be the best available to you.
-
Because comparing offers can be done before formal application,
compare your pre-approved offer against other lenders before
accepting.
Got a pre-approved offer sitting in your inbox?
Compare it against 100+ RBI-registered lenders on SwipeLoan first —
same profile, multiple offers, and compare before you commit.
Disclaimer:
SwipeLoan is a credit-matching loan marketplace and Lending Service
Provider, not a lender. Loan approval, interest rate, fees, tenure,
eligibility and disbursal are determined by the individual lending
partner, subject to its credit policy and applicable regulations.
Terms and conditions apply.